The Impact Of Inflation And Debt On American Families
The Core Problem
Inflation and household debt shape the daily economic reality of American families more than almost any other pair of forces. Rising prices reduce what a paycheck can buy. Rising debt increases monthly obligations and vulnerability to interest-rate changes or income shocks. Understanding the long-term data—going back to the 1960s and earlier where available—is essential for separating rhetoric from measurable trends.
Household Income Over Time
Official Census Bureau data (adjusted to 2024 dollars using chained CPI methods) show real median household income has risen, but the gains have been uneven and slower than many assume.
Approximate real median household income (2024 dollars):
- 1967: $54,880
- 1970: $59,040
- 1980: $60,210
- 1990: $65,440
- 2000: $71,790
- 2019: $83,260
- 2024: $83,730
Nominal incomes were far lower in earlier decades (roughly $7,000 in the late 1960s). After inflation adjustment, the typical household has more purchasing power than in 1967, with most of the real gains occurring from the mid-1990s through the late 2010s. Progress stalled or reversed during high-inflation or recession periods (1970s, early 1980s, 2008–2012, and parts of 2020–2022).
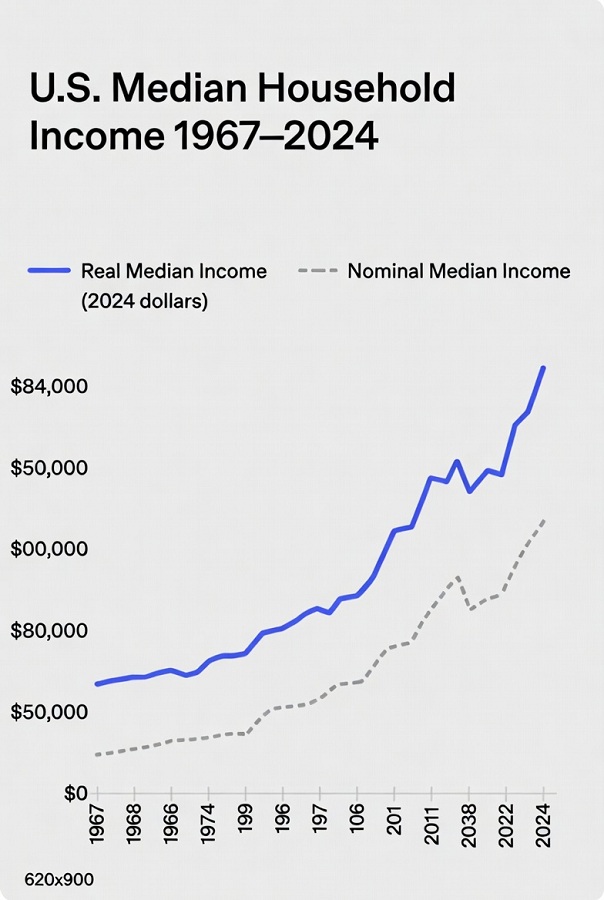
Figure 1. Real vs. Nominal Median Household Income, 1967–2024.
The solid blue line shows inflation-adjusted (real) income in 2024 dollars.
The dashed gray line shows nominal (current-dollar) income.
Real gains have been modest and uneven despite the steep rise in nominal figures.
How To Interpret Income Charts
Always distinguish nominal (current dollars) from real (inflation-adjusted) figures. A rising nominal line can mask stagnant or falling living standards. Look at the slope of the real series: long plateaus indicate periods when income growth failed to outpace prices. Compare medians (typical household) rather than means (pulled upward by high earners). Context matters—household size, dual earners, and non-cash benefits have changed over decades.
Inflation’s Long Record
The Consumer Price Index (CPI) for all urban consumers provides the standard measure. From the early 1960s to the mid-2020s, the overall price level multiplied roughly tenfold. High-inflation episodes were concentrated in the 1970s (peak double-digit years), the early 1980s, and 2021–2023 (peak near 9 percent year-over-year). Cumulative inflation erodes fixed incomes, savings, and wage gains that do not keep pace.
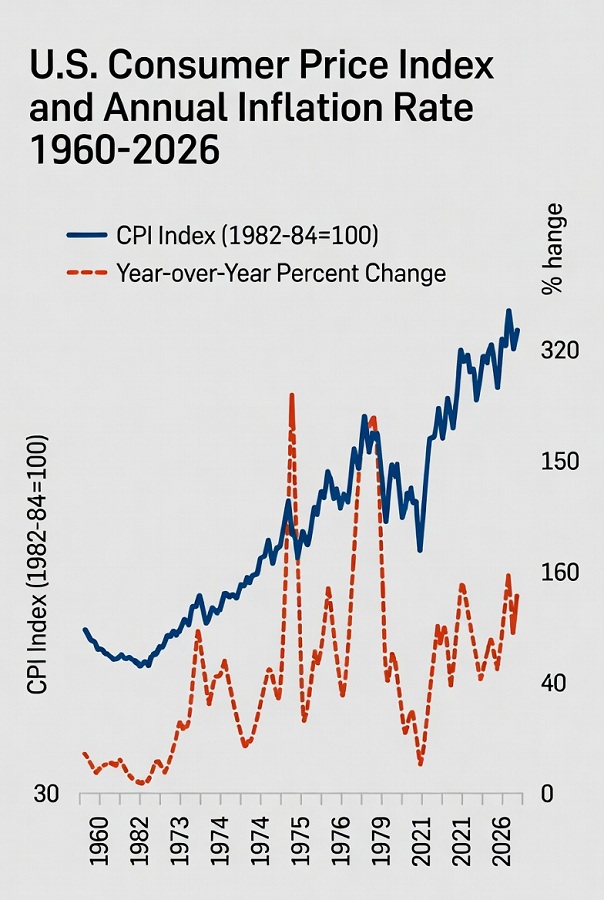
Figure 2. CPI Index Level and Year-over-Year Inflation Rate, 1960–2026.
The solid blue line (left axis) tracks the cumulative price level.
The red dashed line (right axis) shows the annual inflation rate.
Note the sharp spikes in the 1970s, early 1980s, and 2021–2023.
How To Interpret Inflation Charts
Examine both the level of the CPI index and the year-over-year percent change. A steadily rising index shows the long-term loss of purchasing power. Spikes in the percent-change series mark acute cost-of-living crises. Note that official CPI has methodological changes over time; alternative measures (PCE, chained CPI, or specific baskets for housing, food, energy, education, and medical care) can tell different stories for different families. Housing and education costs have often risen faster than the overall index.
Household Debt Load And Ratios
Total U.S. household debt reached approximately $18.8 trillion by early 2026. Mortgages dominate (roughly 70 percent). The remainder consists mainly of auto loans, student loans, and credit cards.
Key ratio trends:
- Household debt-to-GDP rose from the 40–50 percent range in the 1960s–1970s to a peak near 100 percent around 2007–2008, then declined to the low-to-mid 70 percent range in recent years.
- Debt-to-income ratios followed a similar path, peaking near 120 percent before the financial crisis and later settling lower.
- The debt-service ratio (required payments as a percent of disposable personal income) peaked above 15 percent before 2008 and has more recently hovered near 11 percent.
Debt growth after 1980 was driven less by more households borrowing and more by larger amounts borrowed per household, including home-equity extraction.
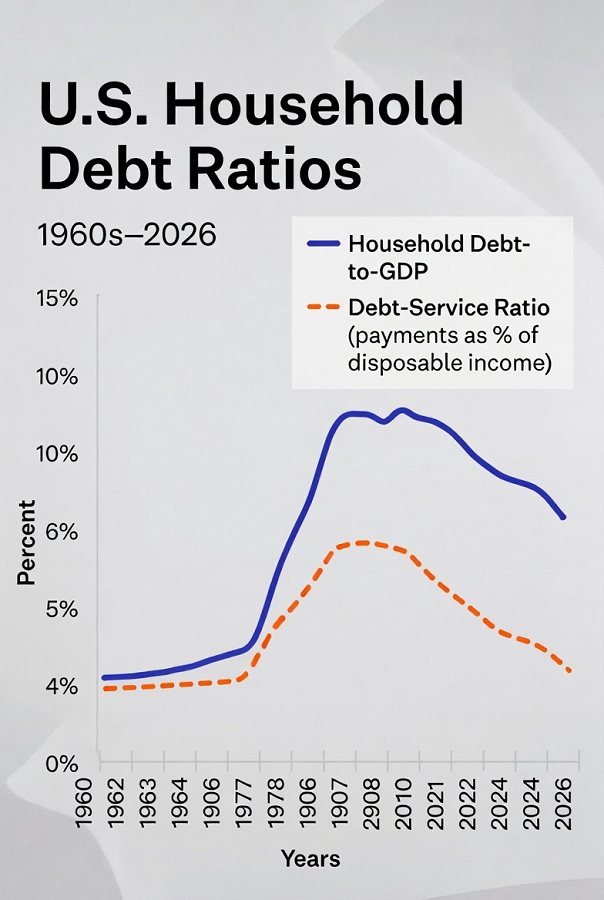
Figure 3. Household Debt-to-GDP and Debt-Service Ratio, 1960s–2026.
The solid blue line shows total household debt relative to GDP.
The dashed orange line shows required debt payments as a percentage of disposable personal income.
Both peaked near the 2008 financial crisis and have since moderated.
How To Interpret Debt Charts
Ratios are more informative than raw dollar totals. Debt-to-income or debt-to-GDP shows leverage relative to the economy’s ability to support it. The debt-service ratio incorporates interest rates and thus better reflects monthly burden. Rising debt is not automatically negative if it finances productive assets (homes, education that raises earnings) at manageable rates. Warning signs appear when ratios climb rapidly while incomes stagnate or when variable-rate or high-interest debt (credit cards, some student loans) expands. Always note the composition: mortgage debt secured by housing differs from unsecured consumer debt.
Combined Impact On Families
When real income growth is modest and inflation or debt-service costs rise, families face tighter budgets. Housing, education, and medical costs have frequently outpaced general inflation, amplifying the squeeze. High leverage increases sensitivity to job loss, rate hikes, or asset-price declines. Conversely, periods of rising real incomes, moderate inflation, and declining debt-service ratios expand breathing room.
The data do not support simple narratives of continuous decline or continuous improvement. Real median income is higher than in the 1960s and 1970s. Debt ratios are lower than their pre-crisis peak. Yet the cumulative effect of inflation, the concentration of cost pressures in essential categories, and the growth of certain non-mortgage debts leave many households feeling strained—especially younger families, those without home equity, or those carrying student debt.
Practical Takeaways
- Track real, not nominal, figures.
- Focus on ratios and debt-service burdens rather than headline debt totals.
- Examine specific cost categories that matter most to your household.
- Distinguish productive debt (that builds assets or human capital) from consumption debt.
- Policy choices on monetary stability, fiscal deficits, housing supply, education costs, and credit standards all influence these trends. Personal decisions on earning, saving, and borrowing remain decisive at the household level.
Call To Action
Review the official sources—Census historical income tables, BLS CPI data, Federal Reserve household debt reports, and the New York Fed Consumer Credit Panel. Compare the long-term charts yourself. What patterns stand out for your own situation or for families you know? Which drivers of inflation or debt growth deserve the most attention? Share evidence-based observations in the replies. Principled discussion of the numbers beats slogans.